NGX recovers 1.36% as weekly turnover value falls 11.1%, despite a sharp rise in share volume.
THE MARKET LAST WEEK
MyReapMoney Weekly Financial Market Intelligence
Week ended Friday, 13 November 2026 | Comparison: 6 November 2026 | Cut-off: Friday close
Executive summary
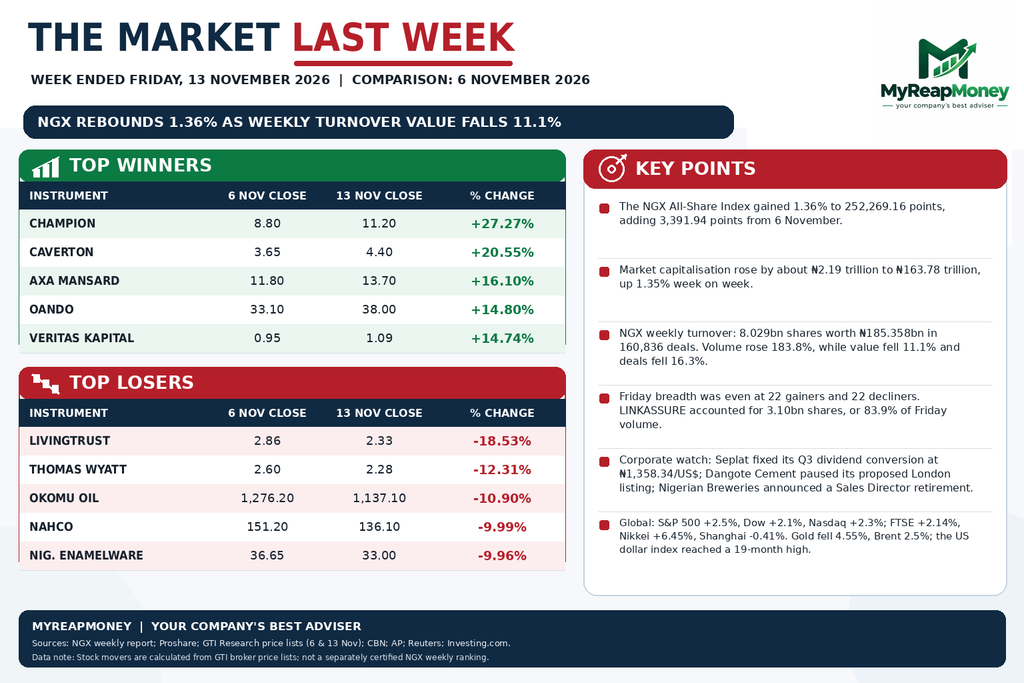
The Nigerian Exchange closed the week ended 13 November 2026 higher, with the All-Share Index rising 3,391.94 points, or 1.36%, to 252,269.16 from 248,877.22 on 6 November. Market capitalisation increased by approximately ₦2.19 trillion to ₦163.78 trillion from ₦161.594 trillion.
The headline index recovery was accompanied by a sharp rise in traded volume, but not in traded value. The NGX weekly report recorded 8.029 billion shares worth ₦185.358 billion in 160,836 deals, compared with 2.829 billion shares worth ₦208.407 billion in 192,158 deals in the preceding week. On that basis, volume rose 183.8%, while value declined 11.1% and deals fell 16.3%.
The volume increase should be interpreted carefully. Proshare reported that LINKASSURE accounted for 3.10 billion shares, or 83.9% of Friday’s volume, indicating substantial concentration in one counter. Friday’s market breadth was balanced at 22 advancers and 22 decliners.
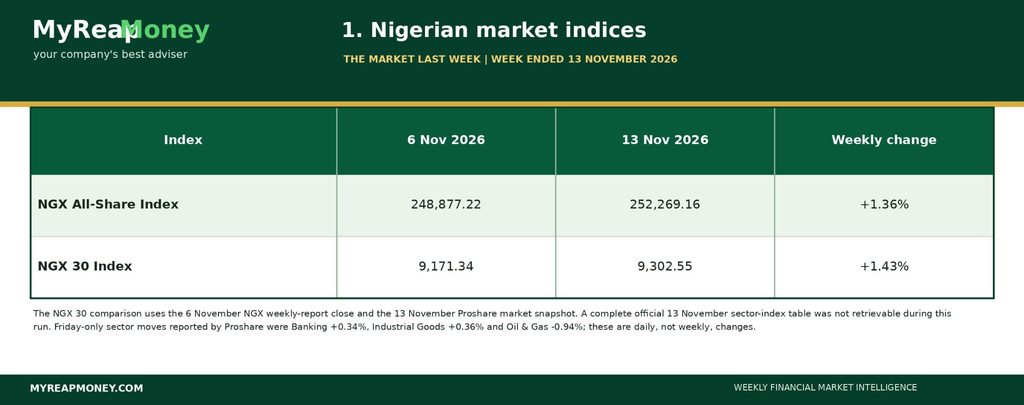
The NGX 30 comparison uses the 6 November NGX weekly-report close and the 13 November Proshare market snapshot. A complete official 13 November sector-index table was not retrievable during this run. Friday-only sector moves reported by Proshare were Banking +0.34%, Industrial Goods +0.36% and Oil & Gas -0.94%; these are daily, not weekly, changes.
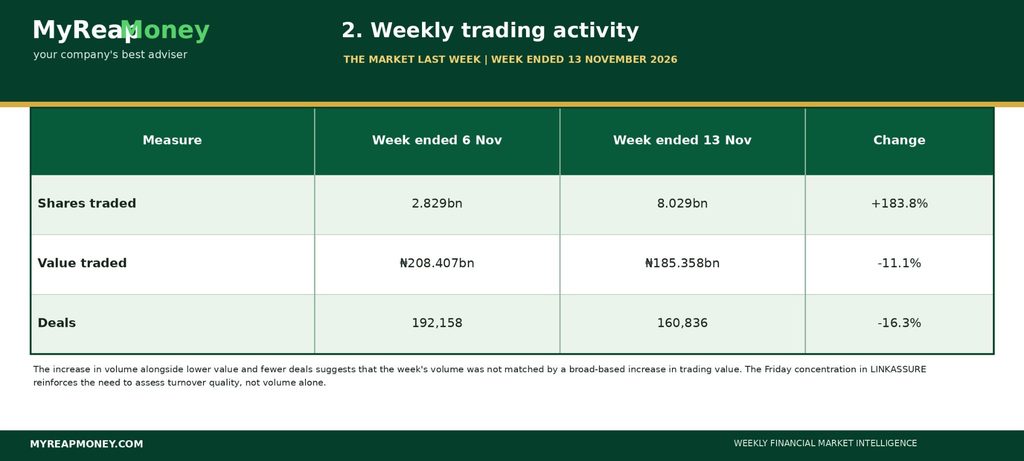
The increase in volume alongside lower value and fewer deals suggests that the week’s volume was not matched by a broad-based increase in trading value. The Friday concentration in LINKASSURE reinforces the need to assess turnover quality, not volume alone.
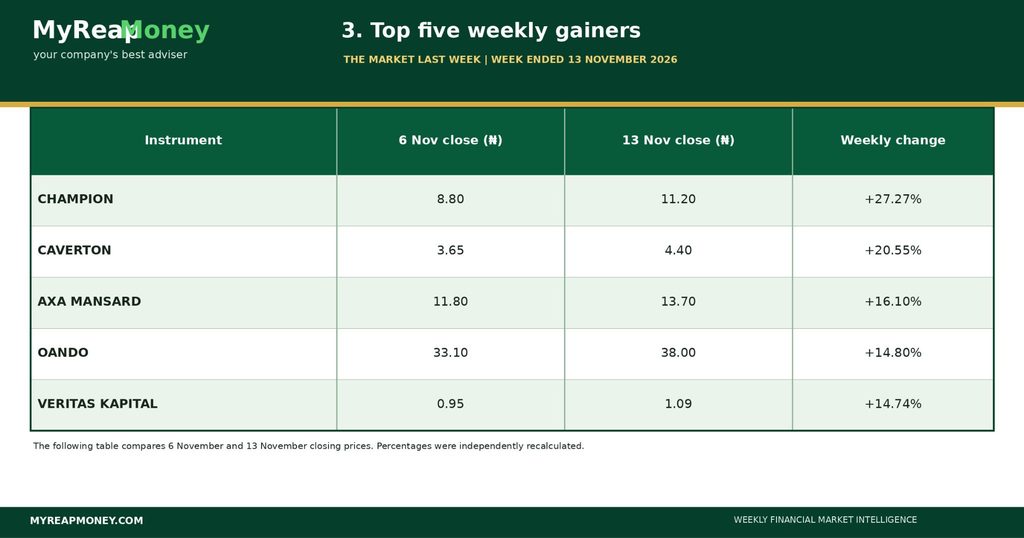
3. Top five weekly gainersThe following table compares 6 November and 13 November closing prices. Percentages were independently recalculated.
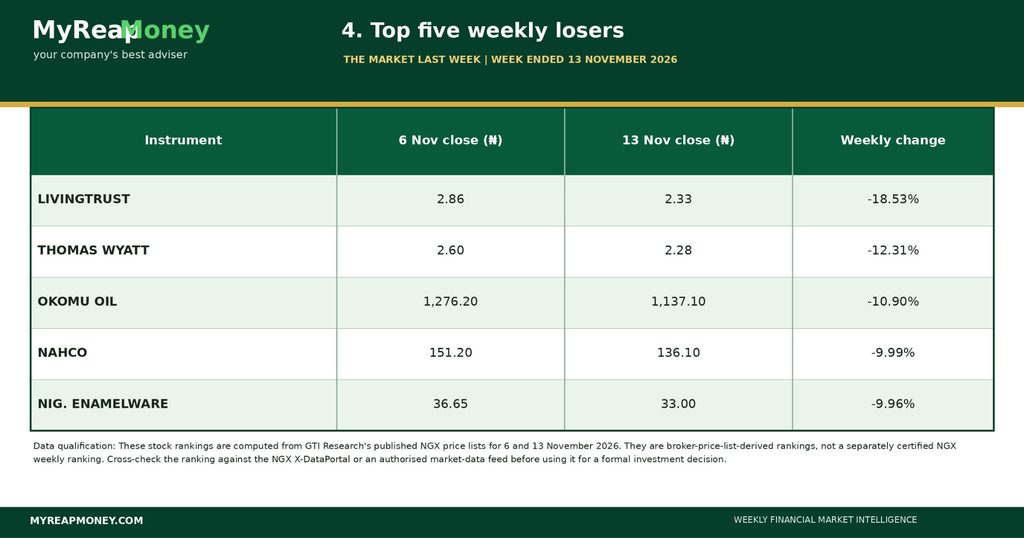
Data qualification: These stock rankings are computed from GTI Research’s published NGX price lists for 6 and 13 November 2026. They are broker-price-list-derived rankings, not a separately certified NGX weekly ranking. The full 13 November NGX weekly report PDF and consolidated historical EOD archive were not retrievable in this run. Cross-check the ranking against the NGX X-DataPortal or an authorised market-data feed before using it for a formal investment decision.
5. Corporate developments
- Dangote Cement: The company and Dangote Industries Limited suspended the proposed secondary listing and share offering on the London Stock Exchange for now, citing prevailing market conditions and strategic priorities. Its NGX listing and operations remain unchanged.
- Seplat Energy: Seplat announced an applicable exchange rate of ₦1,358.34 per US dollar for calculating the naira equivalent of its Q3 2026 interim and special dividends. The combined distribution is 19 US cents per share, comprising 5 cents interim and 14 cents special.
- Nigerian Breweries: The company announced the retirement of Sales Director Emmanuel Oriakhi, effective 10 November 2026, after more than 23 years with Nigerian Breweries and HEINEKEN. A successor is to be announced.
- Access Holdings: An NGX filing dated 11 November disclosed the vesting of company shares to 56 employees under the Group’s share arrangements.
6. Global market context
United States: The S&P 500 gained 2.5% for the week, the Dow Jones Industrial Average rose 2.1% and the Nasdaq Composite advanced 2.3%, even though all three ended Friday lower. Technology shares remained volatile amid Nvidia-related uncertainty and renewed concern about inflation and interest rates. October US producer prices rose 6.5% year on year, their largest annual increase since November 2022. The US dollar also held near a 19-month high as traders weighed the risk of a larger Federal Reserve rate rise.
Other markets: The FTSE 100 rose approximately 2.2% for the week. The Nikkei 225 advanced about 6.45%, calculated from 57,434.77 on 6 November to 61,142.35 on 13 November. The Shanghai Composite declined approximately 0.41%, from 3,649.18 to 3,634.35.
Commodities: Gold fell 4.55% for the week to about US$3,879.70 per ounce. Brent crude settled at about US$95.84 per barrel, down 2.52% on the week. Lower oil prices could weigh on Nigeria’s export receipts if sustained, although the eventual effect depends on production, fiscal flows and timing. Gold’s weekly decline coincided with higher global yields and a stronger US dollar.
Foreign exchange and policy: The CBN official central USD/NGN rate, as republished in 9jaPulse’s daily CBN-rate table, moved from ₦1,346.29 on 6 November to ₦1,353.47 on 13 November. That is a 0.53% increase in naira per dollar, indicating modest naira weakening over the period. The CBN’s Monetary Policy Rate remained at 23%, following the September MPC decision. The next MPC meeting is scheduled for 23-24 November 2026.
7. Key points for investors
- The NGX All-Share Index gained 1.36%, but the Friday close was slightly lower than Thursday’s close after profit-taking.
- Weekly volume rose sharply, but turnover value and deal count declined. Volume concentration in LINKASSURE means the increase should not be treated as a broad liquidity signal.
- The weekly gainers were led by Champion Breweries and Caverton, while LivingTrust and Thomas Wyatt recorded the largest losses in the broker-price-list comparison.
- Dangote Cement’s paused London listing removes a near-term international secondary-offer catalyst, while Seplat’s dividend exchange-rate announcement clarifies the naira conversion for eligible shareholders.
- Global equities ended the week higher in the United States and United Kingdom, but AI-sector volatility and higher inflation expectations remain important risk factors.
- A softer Brent price and modest naira weakening are relevant to Nigeria’s FX and fiscal outlook, but neither should be interpreted as a direct one-for-one driver of the NGX.
8. Investor watchlist
- 1. The CBN MPC meeting scheduled for 23-24 November and its implications for yields, liquidity and the naira.
- 2. Further Q3 financial results, dividend announcements and board decisions, including updates from Dangote Cement and FCMB Group.
- 3. Seplat’s scheduled Q3 interim and special dividend payment around 27 November, subject to the company’s published timetable.
- 4. Brent crude prices, Nigerian production and foreign-exchange inflows.
- 5. Whether NGX trading value broadens beyond concentrated high-volume counters and whether large-cap participation improves.
Executive takeaway
The Nigerian market finished the week stronger, but the quality of the advance was mixed. The 1.36% rise in the All-Share Index and ₦2.19 trillion increase in market capitalisation were positive, yet turnover value and deals fell while volume surged on concentrated activity. Investors should therefore distinguish index recovery from broad market participation. The next signals to watch are trading-value breadth, corporate earnings and dividend actions, the CBN’s November policy meeting, oil prices and the naira.
Data integrity and limitations
The market-data cut-off is the close of Friday, 13 November 2026. Sources retrieved on 14 November were used only for information reporting through that cut-off. The official NGX weekly report for the week ended 13 November was identified and its aggregate turnover figures were available, but the complete PDF was not retrievable in this run. Accordingly, full-week market breadth and the complete official sector-index table are marked unavailable rather than estimated. The stock-mover rankings are explicitly identified as GTI broker-price-list calculations.
Sources
- NGX Weekly Report, week ended 6 November 2026 (official NGX report PDF): https://mondovisione.com/_assets/files/NGX_Weekly-Report-20261106.pdf
- NGX Weekly Market Report, week ended 13 November 2026 (summary distributed through Mondo Visione; full PDF not retrievable during this run).
- GTI Research, NGX Price List Friday, 6 November 2026: https://research.gti.com.ng/ngx-price-list-friday-6th-november-2026/
- GTI Research, NGX Price List Friday, 13 November 2026: https://research.gti.com.ng/ngx-price-list-friday-13th-november-2026/
- Proshare, Profit-Taking Pulls NGXASI Down 0.04% to 252,269.16 Points, 13 November 2026: https://proshare.co/articles/profit-taking-pulls-ngxasi-down-0.04-to-252269.16-points-bdc-rate-flat-at-n1440us1?category=Market+Updates&classification=Read&menu=Market
- NGX Corporate Disclosures: https://ngxgroup.com/exchange/data/corporate-disclosures/
- Seplat Energy, Currency Exchange Rate for Q3 2026 Interim and Special Dividend, 12 November 2026: https://doclib.ngxgroup.com/Financial_NewsDocs/48394_SEPLAT_ENERGY_PLC-CURRENCY_EXCHANGE_RATE_FOR_Q3_2026_DIVIDEND_CORPORATE_ACTIONS_NOVEMBER_2026.pdf
- Access Holdings, Vesting of Shares, 11 November 2026: https://doclib.ngxgroup.com/Financial_NewsDocs/48391_ACCESS_HOLDINGS_PLC-VESTING_OF_ACCESS_HOLDINGS_PLC_SHARES_CORPORATE_ACTIONS_NOVEMBER_2026.pdf
- Nigerian Breweries, Sales Director retirement disclosure: https://doclib.ngxgroup.com/Financial_NewsDocs/48396_NIGERIAN_BREWERIES_PLC-MANAGEMENT_CHANGE_CORPORATE_ACTIONS_NOVEMBER_2026.pdf
- CBN Monetary Policy Decisions: https://www.cbn.gov.ng/MonetaryPolicy/decisions.html
- CBN Exchange Rates: https://www.cbn.gov.ng/rates/exchratebycurrency.html
- Associated Press, How major US stock indexes fared Friday 13 November 2026: https://apnews.com/article/wall-street-stocks-dow-nasdaq-12c1e8155fb85c3c7b09e058ed6d3c74
- Reuters, Global markets, 13 November 2026: https://www.reuters.com/world/china/global-markets-global-markets-2026-11-13/
- IG Wealth Management, The Week in the Markets, 13 November 2026: https://www.ig.ca/en/media-room/the-week-in-the-markets/the-week-in-the-markets-nov13Investing.com,
- Shanghai Composite historical data: https://www.investing.com/indices/shanghai-composite-historical-data
